Commercial Property
Buildings, contents, and business interruption for owners and tenants. Limits reviewed against what the structure actually costs to rebuild, not what it last appraised at.
Family-owned · Woodland Hills · 30+ years
Commercial property, apartment buildings, contractors and fleets — plus the personal policies that sit alongside them. Start here and we'll tell you where you stand.
Rate Check
Step 1 of 8
The part nobody explains
"My GC's policy covers me."
It covers them. Your work, your tools, and your liability are yours — and most general contractors won't let you on site until you produce your own certificate naming them as additional insured.
"My building is insured for what I paid for it."
Property policies pay to rebuild, not to repurchase. Construction costs and code-upgrade requirements move independently of what a building is worth on the market, and a building insured at market value is very often underinsured at claim time.
"Workers' comp is a fixed cost. Nothing to manage."
It's rated on classification codes and your experience modifier. Miscoded payroll is one of the most common ways businesses overpay, and it compounds every year nobody checks it.
"I have the certificate, so I'm covered."
A certificate is a snapshot for whoever asked for it. It confers no coverage on its own. The policy form and its endorsements decide what is actually covered — which is why the additional-insured wording matters more than the certificate does.
"If the building burns, the policy covers my lost rent."
Only if loss of rents is scheduled on the policy. Without it the building gets rebuilt and the months of missing income are yours to absorb — on a mortgage that doesn't pause.
"Builders risk can wait until we break ground."
Cover needs to be in force before materials land on site. Theft and vandalism at unsecured sites are among the most common construction claims, and plenty of them happen before a foundation is poured.
"My homeowners policy covers earthquake damage."
It does not. Standard homeowners policies exclude earthquake, and in California that is not a small gap — it needs its own policy or endorsement. Most people find out the week after they needed it.
"I'm young, I don't need life insurance."
Young and healthy is exactly when it's cheapest. Rates are set at the age you buy and lock in from there — the younger you are, the lower your rate and the stronger your protection.
What we write
Coverage that keeps you open for business — general liability, commercial auto, workers' comp, property and equipment. For building owners, contractors, franchisees and operators across the Valley.
Buildings, contents, and business interruption for owners and tenants. Limits reviewed against what the structure actually costs to rebuild, not what it last appraised at.
Multi-unit dwelling cover for landlords and owners: the structure, loss of rents, and premises liability across the whole schedule.
General liability and business owner's policies for small operations and established firms. Property, liability, and income protection in one place.
General and artisan contractor liability, tools and equipment, and the additional-insured endorsements your GC will ask for before you set foot on site.
Course-of-construction cover for ground-up builds, renovations, and conversions — written for the length of the job and the value at completion.
Single vehicles through full fleets. Liability, physical damage, hired and non-owned, and the certificates your contracts require.
Statutory cover for your crew, with classification codes reviewed properly — miscoded payroll is one of the most common ways businesses overpay.
Third-party bodily injury and property damage, products and completed operations. The policy every contract asks you to produce.
We write these too — for building owners, their families, and their tenants.
The book
Real risks we place across Woodland Hills and the San Fernando Valley — not stock photography. Buildings, builds, fleets and the odd thing that needs its own form.
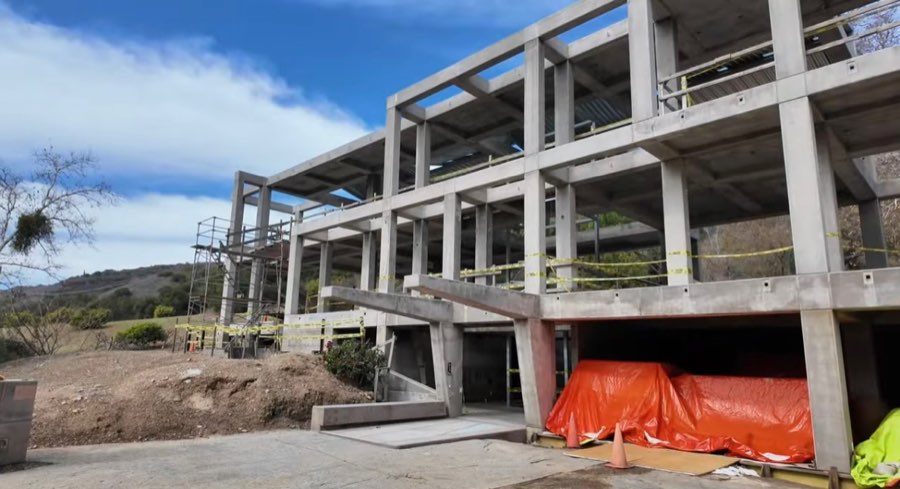
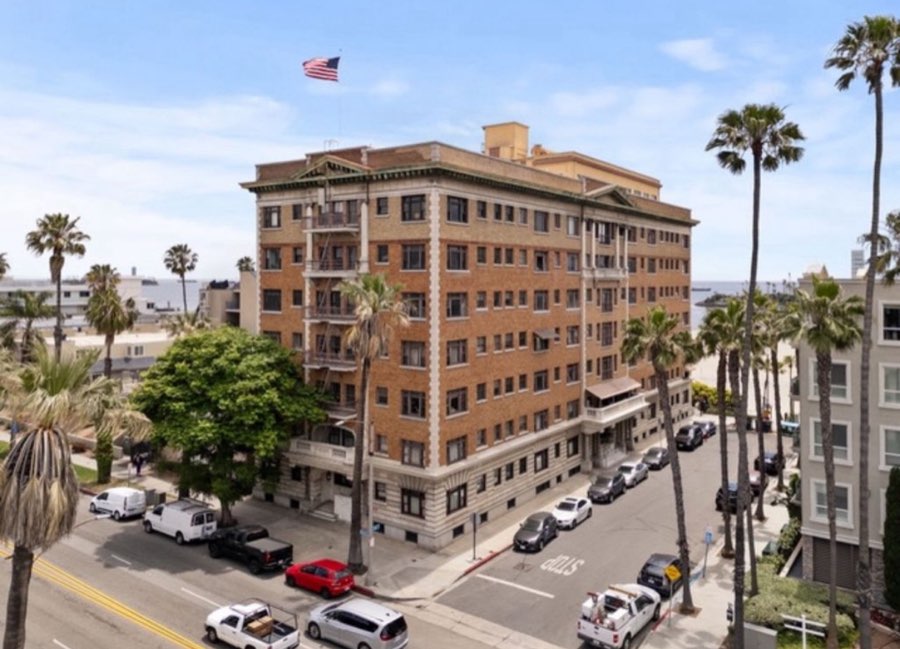
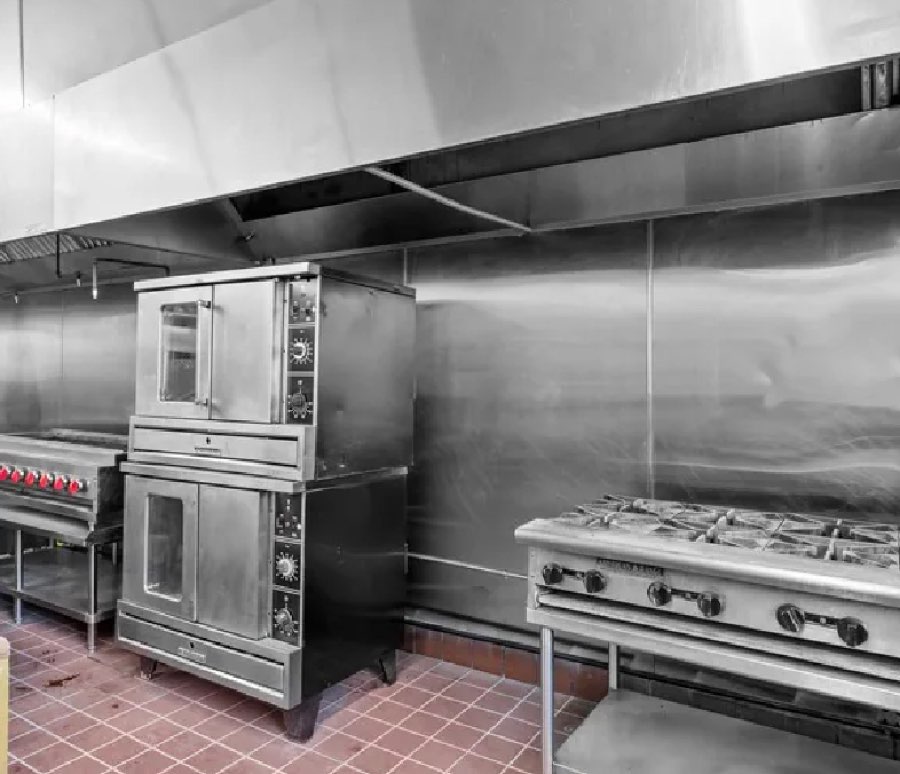
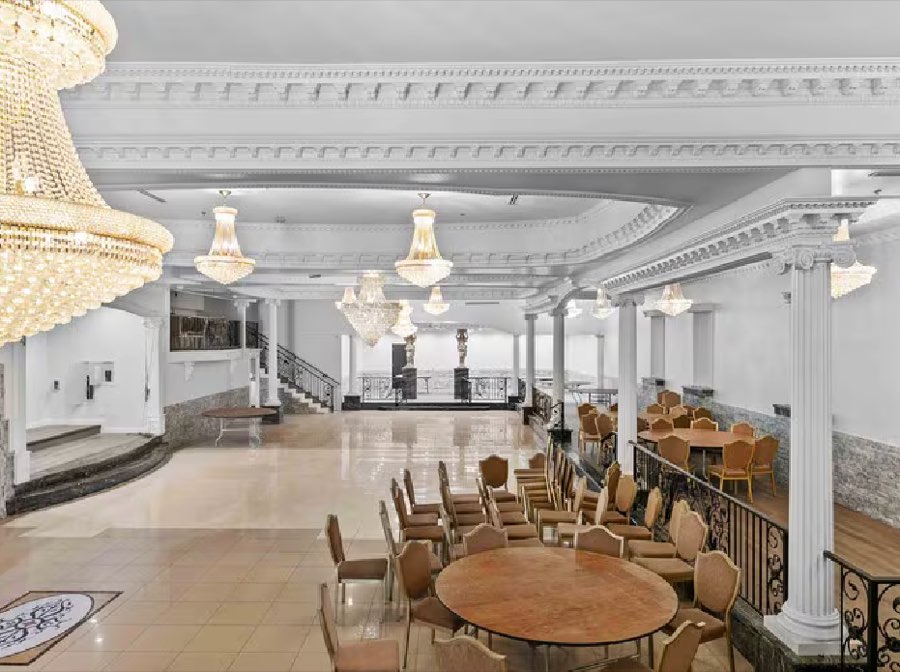
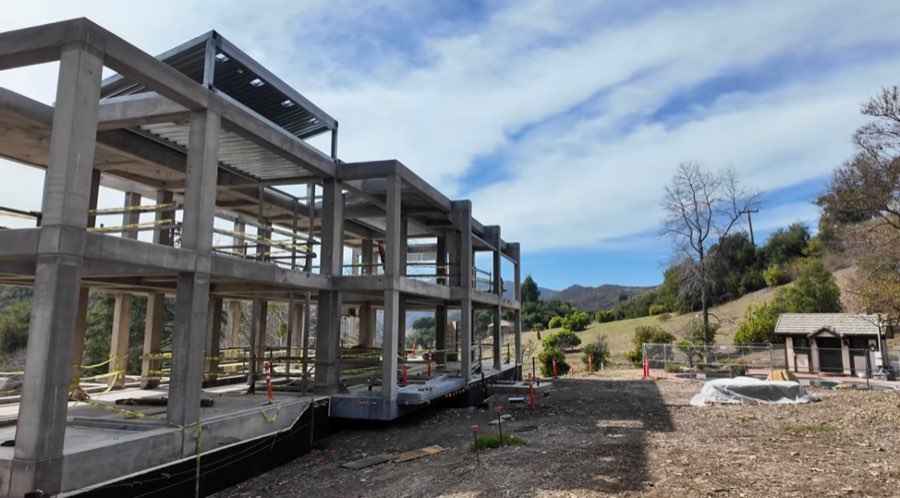
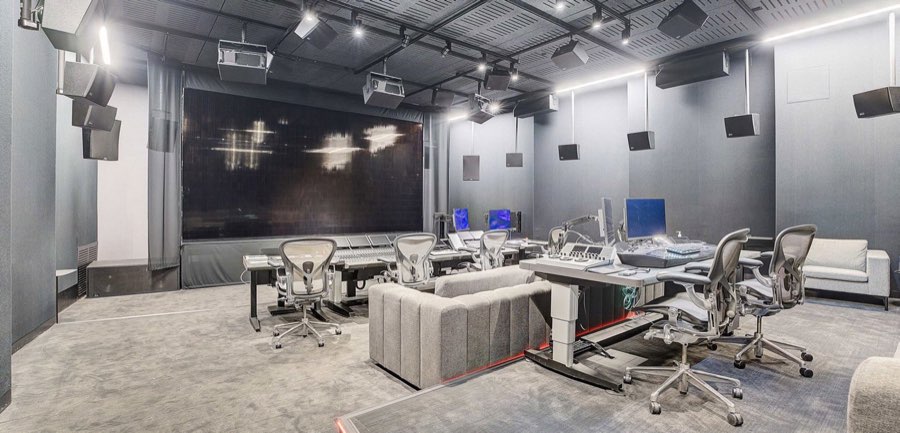
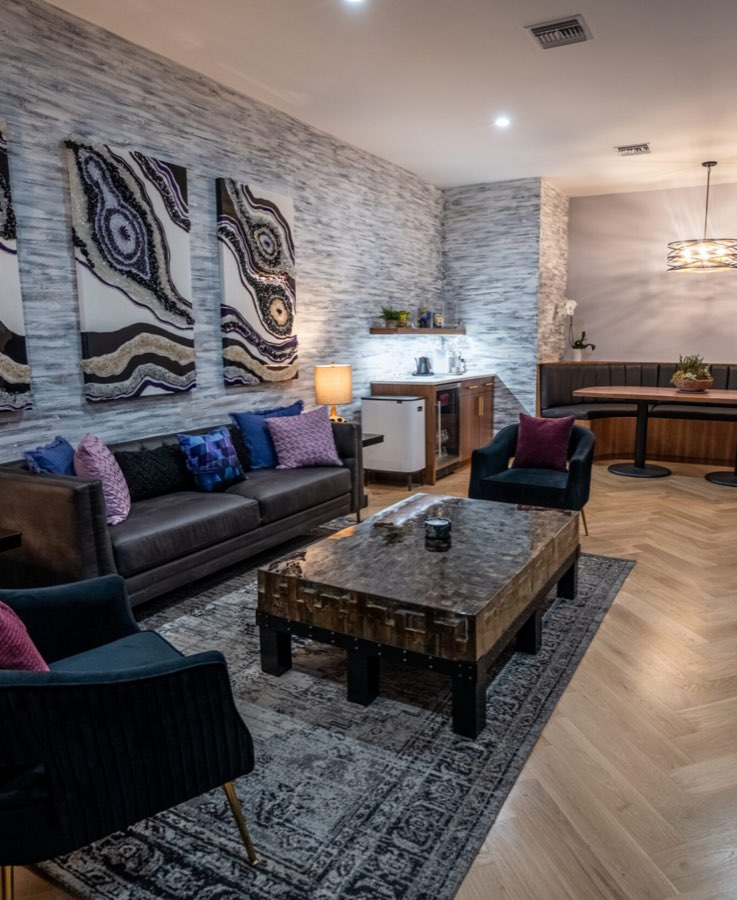
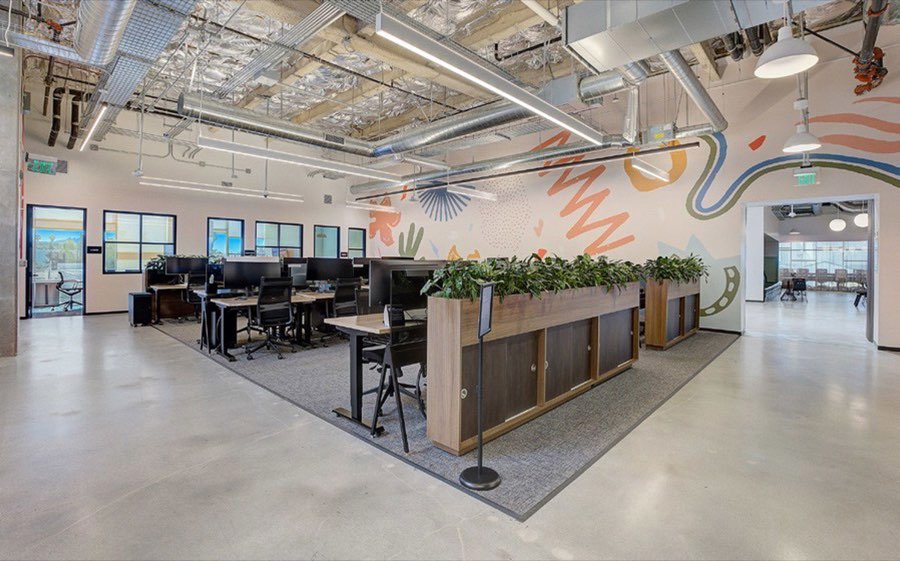
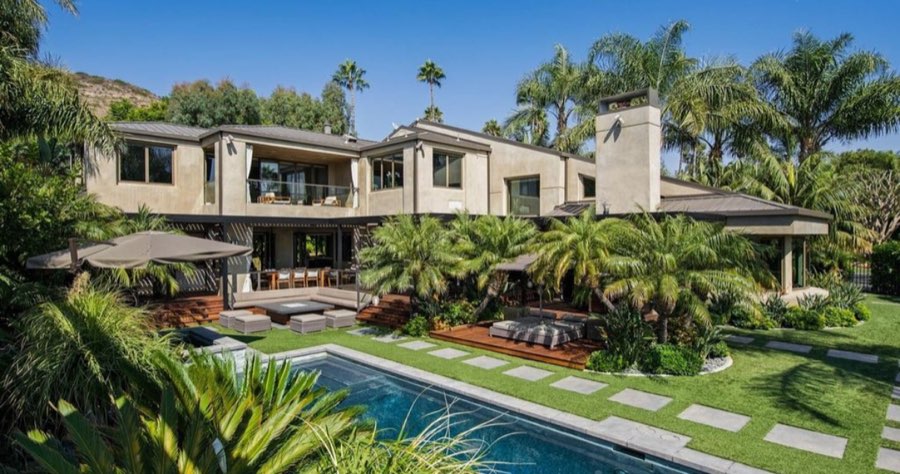
Client properties, shown with permission. No addresses or identifying details are published.
Know your exposure
Every trade carries its own worst day. Here's where the exposure usually sits — and what we look at first when we price it.
| Business type | Main risk | Exposure |
|---|---|---|
| Retail & Hospitality | Customer injury, slip & fall | High |
| Construction & Contracting | Property damage, injury | Very high |
| Professional Services | Errors & omissions | Moderate |
| Manufacturing | Product defects, pollution | Very high |
| Transportation | Auto accidents | Extremely high |
| Technology | Cyber breaches, IP issues | Moderate–high |
| Real Estate | Premises liability, E&O | Moderate–high |
General guidance, not a rating. Your actual exposure depends on payroll, revenue, claims history, and how the work is actually done.
Start to bound
A few questions, no account. You get an estimated monthly range built from general rating factors — enough to know whether you're in the right neighborhood.
We take your real details to our appointed carriers and come back with actual, bindable pricing and the coverage differences in plain English.
Pick the option that fits. Nothing is in force until a licensed agent confirms it in writing and the carrier issues the policy.
A real person, not a call center
Skip the tool. Call and get a straight answer about what you're paying now, what you're actually covered for, and whether it's worth moving.
Jack Sorfazian Licensed Agent · CA Lic. #4463471
In their words
I had an excellent experience working with Jack. He helped me set up both my car insurance and business liability insurance and made the entire process smooth and stress-free.
Hovik G. Google review
He didn't just put me into any policy. He explained very thoroughly every step of the process and kept full transparency. I highly recommend Jack for any looking to get Home and Auto.
AJ P. Google review
After what felt like absolute hell trying to get homeowners insurance in California, Jack was our guy. He literally pulled off what multiple others told us was impossible.
R.N. Google review
He's always there for me, very responsive, and ready to help whenever I have questions. Switching to him saved me so much money, and the process was easy and stress free.
Georges A. Google review
Jack and his team are very responsive and they work with you to get you the best deal that suits your needs.
Martel R. Google review
He's the best in the biz and quick too!
Tai S. Google review
Quoted verbatim from Google reviews. Full names and complete reviews are on our Google Business Profile.
Questions
No. For home, auto and renters it's an estimate built from general rating factors — area, age band, coverage level, record, and how long you've been continuously insured. Your real price is set by the carrier once they see your full details. Treat the range as a sanity check, not a bill. Commercial risks don't get an instant number at all, because they're underwritten individually — an agent prices those properly.
Yes, to see the estimate — an agent needs a way to reach you if you want real pricing. The SMS consent box is separate and unchecked by default. Leave it unchecked and we'll only ever call or email you.
We aren't employed by one carrier, so we aren't limited to one carrier's pricing or appetite. We're appointed with several and we place your risk with whichever one fits it best that year.
If the policy is already with us, usually the same day. If it's a new placement, tell us the deadline when you call — carriers move at very different speeds and part of our job is knowing which one can meet yours.
Yes, along with renovations and conversions. It's written for the length of the job and the value at completion, and it needs to be in force before materials arrive on site — not on the day you break ground.
Usually one of two things: your experience modifier moved, or payroll is sitting in the wrong classification codes. Both are worth auditing. Miscoded payroll quietly compounds year over year, and it's one of the most common places we find money.
Yes — single buildings through multi-property schedules, including loss of rents and premises liability across the portfolio. Bring the schedule and the loss runs and we'll work it properly.
No Social Security number, no driver's license number, no full date of birth, and no exact address. A ZIP code and a size band are enough to start, and we'd rather not hold data we don't need.
We're licensed in California and write across Woodland Hills and the San Fernando Valley. Enter your ZIP in the Rate Check and it will tell you straight away, or just call us.
You see your estimated range immediately. A licensed agent follows up within one business day if you want real, bindable pricing. No coverage is in force until an agent confirms it in writing.